Homeowner Guides
Should You Renovate Before You Sell Your Atlanta Home?
Choose the work that earns its place in your budget. A practical guide to repairs, cosmetic updates, selling as-is and paying for pre-sale improvements.
The short answer
- Repair first. Address safety, leaks and visible deferred maintenance before spending on finishes.
- Refresh selectively. Paint, lighting, floors and curb appeal may matter more than a brand-new kitchen.
- Let nearby sales set the budget. Compare as-is and updated homes, then subtract project costs and carrying costs.
- Choose funding last. An available loan or promotional rate does not make an unnecessary project worthwhile.
No renovation guarantees a higher price. Your home's condition, competing listings and timeline should drive the decision.
Should you redo the kitchen before listing, or let the next owner make it their own? The useful answer is not a universal yes or no. It is a comparison: what could this home sell for today, what might a focused refresh change, and what would you keep after paying for the work?
In Morningside-Lenox Park and other intown Atlanta neighborhoods, original details can be part of a home's appeal. Replacing a sound feature simply because it is older can spend money without solving a buyer concern. The goal is to make the house feel cared for, not erase its character.
Start With the Updates Buyers Notice
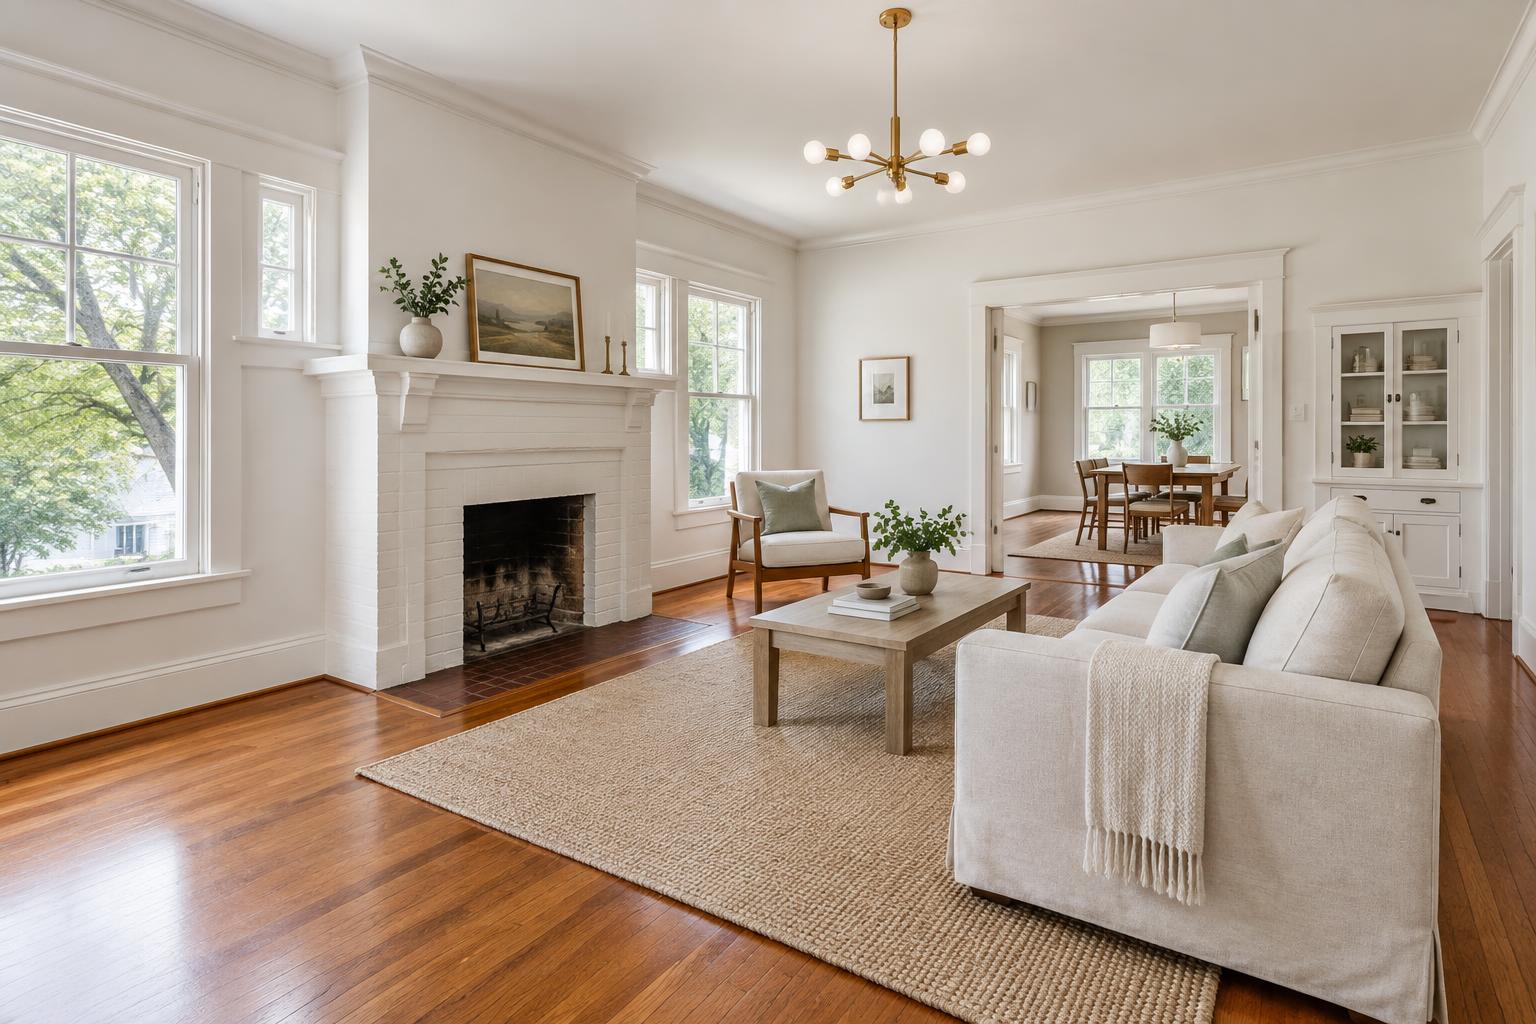
Think clean, bright, cared for — not completely rebuilt.
Before ordering materials, walk through the home as a buyer would: from the curb, through the front door and into the main living spaces. What feels neglected? What makes a room look smaller or darker than it is? Those observations often produce a better scope than a long wish list.
Paint and surface repairs
Patch damage and refresh visibly worn surfaces. A consistent neutral palette can connect rooms without replacing cabinets or altering the floor plan.
Hardwood floors
Clean and assess original floors before deciding to refinish. Refinishing may make sense for widespread wear; spot repairs may be enough elsewhere. Plan around drying time and furniture removal.
Lighting and small details
Replace broken fixtures, use consistent light temperatures and fix loose hardware. Keep improvements appropriate to the house rather than choosing expensive statement pieces.
Curb appeal
Clear overgrowth, clean the front walk and address a tired entry. Modest planting and maintenance can improve the first impression without an elaborate landscape redesign.
Editing and staging
Remove excess furniture, deep-clean and make each room's purpose clear. Ask whether occupied staging, a few rental pieces or full vacant staging is justified for this home.
Fix Problems That Can Derail a Sale
A cosmetic refresh should not hide a repair that needs attention.
Known roof leaks, moisture, unsafe electrical work and failing systems deserve a different conversation from paint colors. Obtain qualified assessments and written estimates. During due diligence, buyers may put a larger allowance on an unknown problem than the actual repair would cost.
A pre-listing inspection can help identify surprises, but it is not required for every sale and it may reveal matters that need disclosure. Discuss the scope with your agent, keep repair records and ask a Georgia closing attorney about disclosure obligations when you are unsure. Never cover up a defect instead of addressing or disclosing it.
- Roof leaks, damaged flashing and failing gutters
- Drainage issues, crawlspace moisture and evidence of water intrusion
- Electrical safety concerns and questionable past work
- Rot, damaged exterior surfaces and neglected mechanical systems
When a Bigger Renovation Is the Wrong Move
A full remodel has to clear a much higher financial bar.
A new kitchen, bathroom addition or layout change can involve design decisions, permits, contractor availability and unexpected conditions behind the walls. That means both a bigger bill and a later listing date. Buyers may still prefer different finishes, even after you have paid for yours.
Start with a smaller alternative: repair cabinet doors, update hardware, improve lighting and address worn finishes. If competing homes show that the existing kitchen is a meaningful pricing obstacle, get a complete estimate before deciding whether more substantial work is warranted.
In historic or otherwise regulated areas, exterior changes, additions and tree work need extra care. Check the rules for the specific property rather than assuming every house in a neighborhood has the same restrictions.
Read the intown renovation & permits guideWhen Selling As-Is Makes More Sense
Sometimes the right renovation budget is a smaller one — or none at all.
Selling as-is can be sensible when the home needs major work, the likely buyer wants to renovate anyway, or your priority is a simpler and faster transition. An estate, a move already underway or limited available cash can make an extensive project impractical.
As-is does not mean you cannot clean, declutter or improve the presentation. Nor does it automatically eliminate inspections, negotiations or disclosure obligations. The key is pricing the condition honestly and explaining what is known, with documents where available.
Compare likely net proceeds from both paths. A renovated home with a higher sale price can still leave you with less money if the work, financing and extra months of ownership consume the difference.
Compare the Net — Not Just the Sale Price
Build two scenarios before you sign a contractor agreement.
Use recent comparable sales with similar size, location and condition, then account for today's competing homes. An updated property on a different street or with a larger footprint is not proof that your project will earn the same premium.
Illustration only: suppose a focused refresh costs $15,000 and you estimate it might increase the sale price by $25,000. That leaves a $10,000 difference before financing costs, additional taxes, insurance, utilities, selling expenses and unexpected work. If the price increase is only $10,000, the project is already behind before those other costs.
Get itemized bids, identify exclusions and set a contingency appropriate to the scope. Keep money available for your next move. Do not commit every dollar of expected equity to a project whose payoff depends on a sale that has not happened.
As-is scenario
Estimated sale proceeds in today's condition, less your loan payoff and selling expenses.
Refresh scenario
Estimated refreshed sale proceeds, less the loan payoff, selling expenses, renovation, financing and extra ownership costs.
The decision
Is the potential difference large enough to justify the work, uncertainty and time? If not, reduce the scope or sell as-is.
A Practical Plan From Walkthrough to Listing
Compare nearby sales
Separate renovated homes from original-condition homes and look at what buyers are actually choosing.
Separate repairs from improvements
Handle safety and condition concerns first. Rank cosmetic work by visibility and likely buyer impact.
Price the complete scope
Get written estimates, check permits and contractor qualifications, and include time and contingency.
Choose affordable funding
Compare the options below and plan for a delayed sale, not just your ideal closing date.
Work backward from photography
Allow for repairs, cleanup, curing or drying, staging and a final walkthrough before the home is photographed.
Funding the work
How to Pay for Pre-Sale Improvements
First choose the right projects. Then choose the right way to pay.
There is no single best funding method. The right fit depends on the project size, available savings, equity, credit profile and how long you can carry the balance if the home does not sell on schedule. Compare total cost, not just the first month's payment.
For eligible Compass sellers, Concierge can front approved pre-sale work such as staging, paint, floors and landscaping, subject to written program and lender terms. That may help preserve cash for your move, but the approved budget should still be based on the work the house actually needs.
- 01Cash or savings
- When it may fitA manageable refresh when you can preserve an emergency reserve and moving funds.
- Cost & repaymentNo borrowing interest; money is tied up until the sale.
- What to watchDo not drain your reserves. Delays and unexpected repairs still need cash.
- 020% introductory APR card
- When it may fitA smaller project you can repay within an eligible purchase promotion — for example, an illustrative 18-month offer.
- Cost & repaymentRequired monthly payments continue. The regular APR applies to any remaining balance after the promotion ends.
- What to watchCheck purchase eligibility, fees, credit limits and contractor surcharges. An 18-month promotion is an example, not a guaranteed current offer.
- 03Compass Concierge
- When it may fitEligible Compass sellers funding approved preparation work without paying the project cost up front.
- Cost & repaymentRepayment is triggered by sale, listing termination or 12 months from the Concierge start date; lender terms may include other triggers.
- What to watchFees or interest may apply depending on your state. Review the current agreement; repayment does not always wait for a sale.
- 04HELOC or home-equity loan
- When it may fitOwners with sufficient equity and time for lender approval; a line of credit can suit staged expenses.
- Cost & repaymentHELOCs commonly have variable rates; equity loans provide a lump sum. Compare closing costs and early-closure charges.
- What to watchYour home secures the debt. Nonpayment can risk foreclosure. Ask about an upcoming listing and how the balance will be paid off at sale.
- 05Personal or contractor-arranged loan
- When it may fitA defined project when an unsecured loan is more suitable than using home equity.
- Cost & repaymentCompare APR, origination fees, monthly payments and any prepayment terms across lenders.
- What to watchContractor financing is still financing. Separate the project price from the loan terms and compare independent offers.
A sale date is not a repayment plan. Choose funding you can carry if the home takes longer to sell, and compare written terms before committing. This is general information, not lending, tax or financial advice.
0% APR Is Not the Same as Deferred Interest
The wording of the offer matters as much as the advertised rate.
With a true 0% introductory purchase APR, interest is not charged during the promotional period. If you still owe money when it ends, the regular rate generally applies to the remaining balance going forward. Minimum payments are still required, and the agreement governs eligibility and late-payment consequences.
A deferred-interest offer often says 'no interest if paid in full.' Interest can accrue from the purchase date and be charged if the promotional balance is not fully paid by the deadline. That can be a very different outcome from a true 0% introductory APR. Read the agreement rather than relying on a headline.
For illustration, $9,000 divided over 18 months is $500 per month, before any fees. Paying only the card's minimum may not clear it in time. Plan to finish early, confirm how payments are allocated and do not rely solely on the home selling before the promotion expires.
A balance-transfer promotion may not apply to new purchases, and transfers or cash advances can carry separate fees and rates. A large new balance can also affect your credit profile. If you are buying your next home, speak with that lender before opening a card or taking out renovation debt.
Keep the Work and the Sale on the Same Timeline
Preparation, pricing and marketing should support one plan.
If appropriate for the property and consistent with current MLS and brokerage rules, Compass Private Exclusives or Coming Soon may help coordinate early marketing with the preparation schedule. Compass One can help keep the transaction information in one place. These are supporting tools, not a substitute for completing the right work and choosing a defensible price.
My starting point is the house, not a program: what should be repaired, what should be left alone and what nearby buyers are paying for. Once we have that answer, we can compare an as-is listing with a focused refresh and choose a launch plan that fits your circumstances.
What would your home sell for as-is versus refreshed?
Let's compare nearby sales and narrow the project list before you commit to the work.